Share
Main Conclusions
- 1. The Argos Index® edges up to 8.9x EBITDA in Q3 2026, while fund and strategic buyer multiples converge.
- 2. Fund multiples fall back to 9.0x under higher financing costs, while strategic buyer multiples rise to 8.8x; sector mix also contributes to this convergence.
- 3. A record 32% of deals are priced below 7.0x EBITDA. The share of deals priced above 15.0x EBITDA rebounds from its historical lows to 8%, driven by strategic buyers.
- 4. Mid-market M&A activity edges down only slightly in Q3 2026, despite major macroeconomic disruption, reflecting the mid-market structural resilience.
- 5. LBO activity holds up, backed by strong direct lending, with sponsors tilting towards smaller tickets
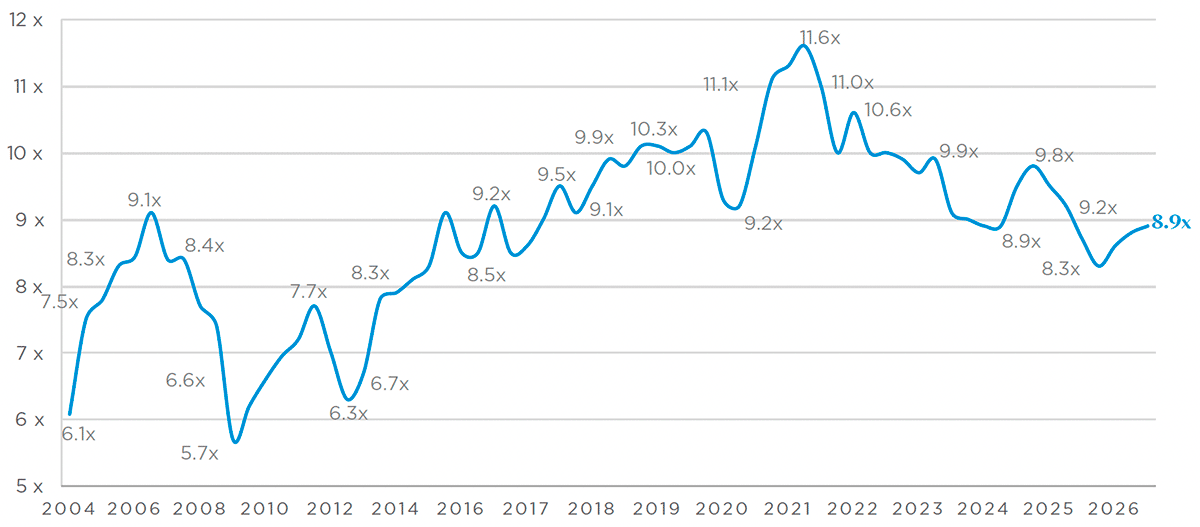
The Argos Index® edges up to 8.9x EBITDA in Q3 2026, while fund and strategic buyer multiples converge
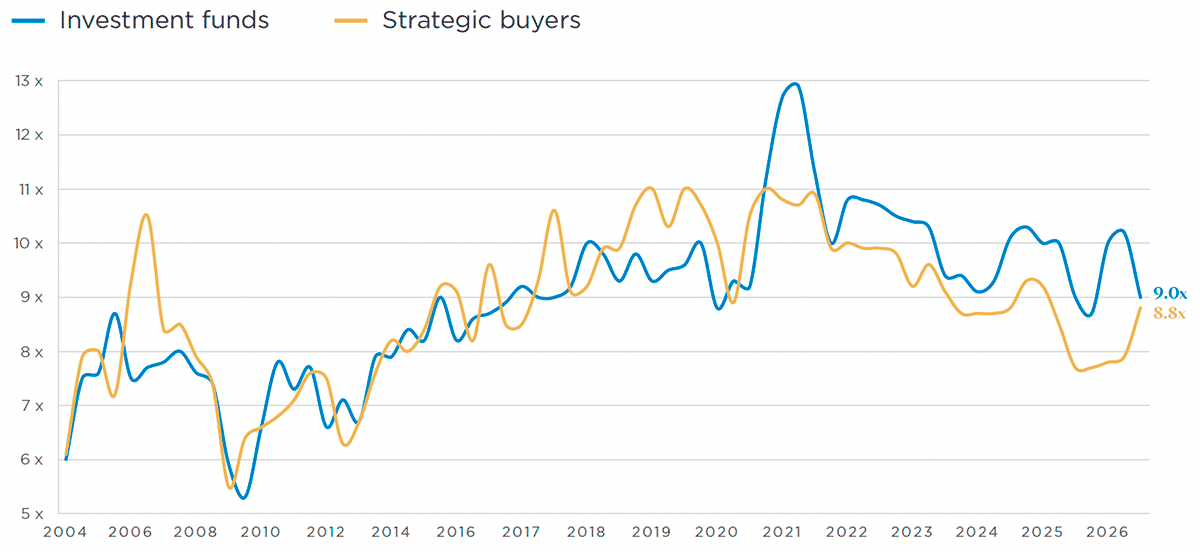
The Argos Index® edges up to 8.9x EBITDA in Q3 2026, its third consecutive quarterly increase, although at a slow pace. The lower mid-market (€15–150m) edged up to 8.5x, while the upper mid-market (€150–500m), which drove the increase in Q2, eased to 9.2x. Behind this apparent stability, the two buyer groups moved in opposite directions: investment fund median multiples fell back to 9.0x EBITDA, while strategic buyer multiples rose to 8.8x, narrowing the gap between them to 0.2x, from 2.3x in Q2.
Overall prices, as well as mid-market deal activity, held up despite a markedly tougher macro-financial environment. Long-term eurozone rates rose sharply over the quarter(1), reaching their highest level since 2012, as the energy shock linked to the Iran conflict pushed up inflation and led the ECB to raise its deposit rate again in September, to 2.50%. The impact of higher rates fell mainly on prices paid by LBO funds, whose leveraged structures make them more sensitive to financing costs, while strategic buyers, less reliant on debt, paid higher multiples.
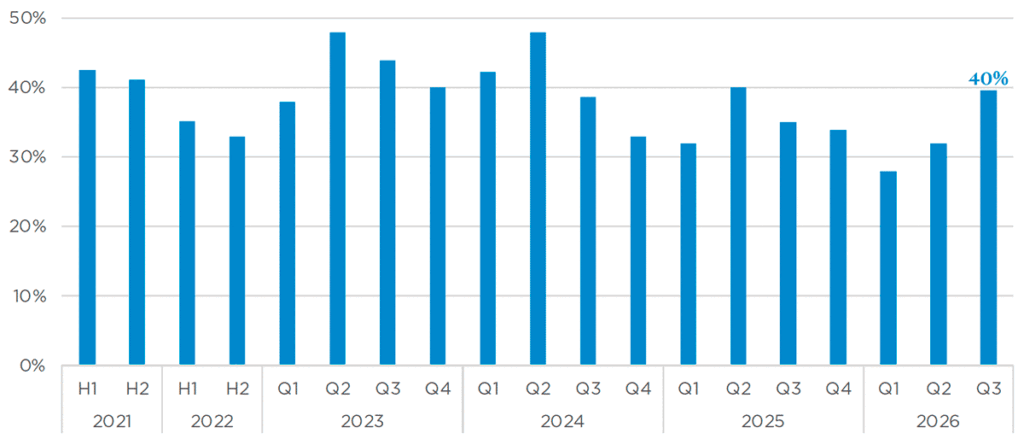
The distribution of multiples also widened: the share of transactions above 15.0x EBITDA increased to 8%, from a historical low of 5% in Q2, driven by strategic buyers, while the share below 7.0x EBITDA rose to 32%, from 27%. Transactions at the extremes thus accounted for 40% of the sample. This polarisation points to growing differentiation between assets rather than a uniform repricing of the market, with corporates paying premium prices for strategic targets, while a growing share of deals closes at lower multiples under tighter financing conditions.
The rebound that began in Q1 2026 has therefore held, but lost momentum, and its composition has changed, with sector mix also contributing to the convergence between fund and strategic buyer multiples. Whether this convergence marks a lasting adjustment, with sponsors absorbing higher financing costs, or a temporary composition effect will be clearer in the coming quarters.
(1) The 10y EU bond yields, calculated by the ECB, rose ~50bp in Q3 2026 (to 3.93% in September)
Argos Index® mid-market
Median EV/EBITDA multiple on a six-month rolling basis
Source : Argos Index© mid-market / Epsilon Research
Fund and strategic buyer multiples converge, with the gap at its narrowest since 2021
Multiples paid by investment funds fell back to 9.0x EBITDA in Q3 2026, from 10.2x in Q2, giving up most of the rebound that began after a low of 8.7x in Q4 2025. Strategic buyer multiples, by contrast, rose to 8.8x from 7.9x, their highest level since Q1 2025. As a result, the gap between fund and strategic buyer multiples narrowed to 0.2x, from 2.3x in Q2, its lowest level since Q4 2021, ending the divergence observed in H1 2026.
The pullback in fund multiples reflects the sharp rise in long-term eurozone rates over the quarter, which weighs directly on leverage capacity and on the prices sponsors can afford to pay. In Q3, sponsor activity tilted towards smaller tickets, which typically trade at lower multiples, adding a mix effect to the pressure from higher rates.
The convergence also reflects sector mix. Fund-led deals are now less concentrated in higher-multiple segments than in H1, and multiples were less dispersed across sectors in Q3. Technology and healthcare accounted
for around a fifth of fund-led deals, against around a third of strategic acquisitions, while business services, at around a quarter, remained a key focus of sponsors.
The rise in strategic buyer multiples also reflects the nature of corporate acquisitions. Corporates continued to pursue strategic deals to gain scale and strengthen their capacity to invest, notably in technology and AI. Their financing capacity, based on balance sheets and operating cash flows rather than acquisition debt, was less sensitive to rising rates. In addition, the Q2 rally in equity markets has fed through with a lag into the valuation references corporates use for acquisitions, while the index held broadly flat in Q3(1).
(1) The EURO STOXX TMI Small Index decreased 0.3% in Q3 2026 and increased 4.8% since 1st Jan. 2026.
Enterprise value / historical EBITDA
Source : Argos Index© mid-market / Epsilon Research
The distribution widens at both ends, with a record share of deals below 7.0x EBITDA
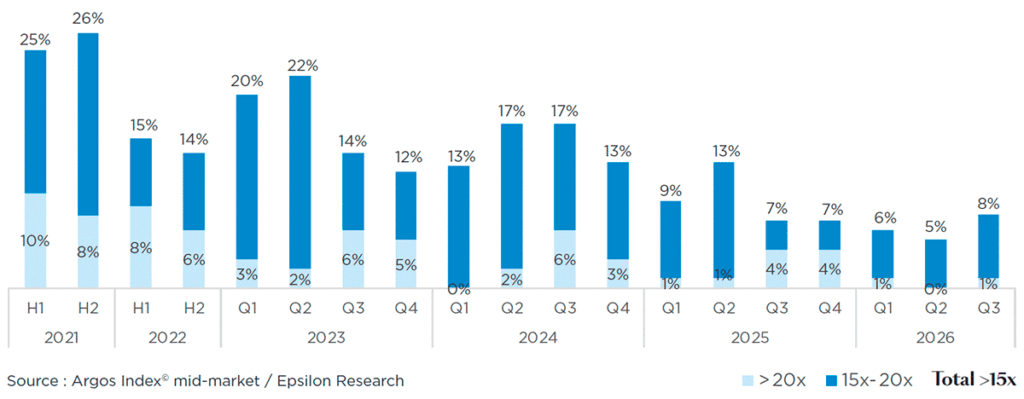
The share of transactions priced at extreme multiples rose to 40% of the Q3 2026 sample. Both ends contributed: the share above 15.0x EBITDA increased to 8%, although it remains below its long-term average of 15% (2018-2026). Transactions above 20.0x EBITDA remained marginal, at 1% of the sample.
Share of transactions at extreme multiples (15x EBITDA)
Source : Argos Index© mid-market / Epsilon Research
Share of transactions at multiples >15x EBITDA Argos Index® sample
Source : Argos Index© mid-market / Epsilon Research
The share of deals priced below 7.0x EBITDA rose further to 32%, its highest level since the series began in 2018. At the other end, the rebound in deals above 15.0x EBITDA was driven by strategic buyers, which accounted for three quarters of these transactions. They involved electrical and electronic equipment, a segment benefiting from investment in electrification and digital infrastructure, as well as business services and software.
Share of transactions at multiples 15x EBITDA Argos Index® sample
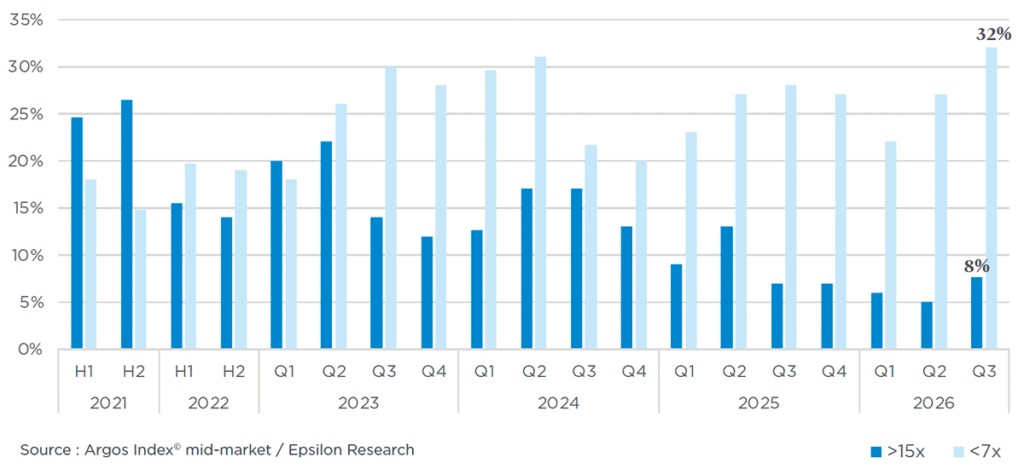
Mid-market M&A activity edges down in Q3 2026, against a troubled backdrop
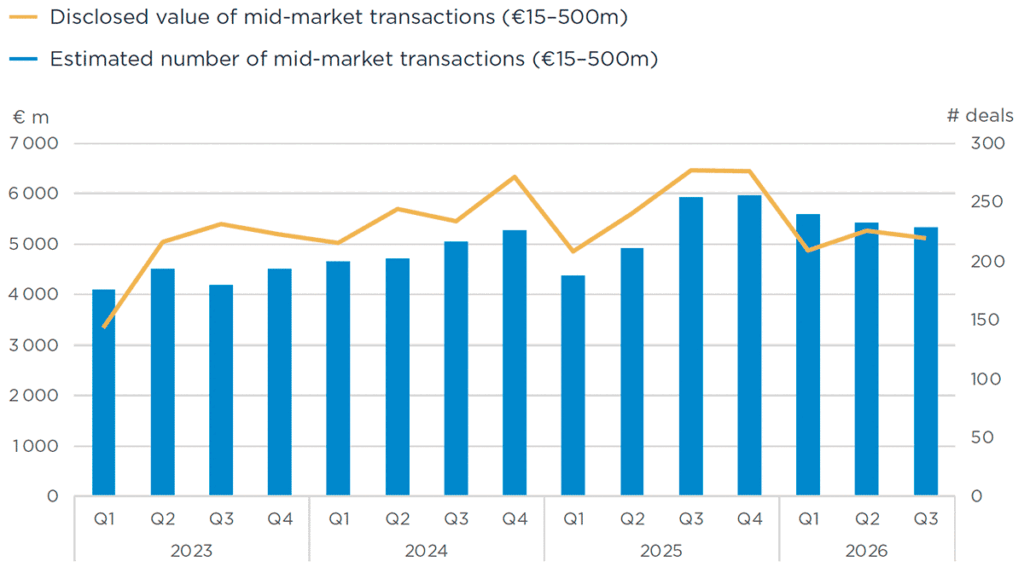
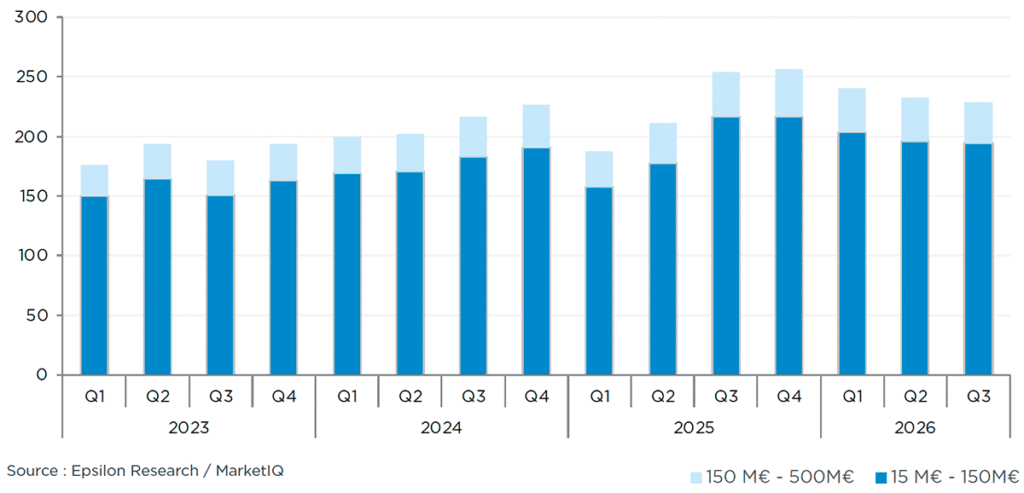
Eurozone mid-market deal activity continued to decline gradually in Q3 2026, with estimated deal volume down 2% quarter-on-quarter(1), a third consecutive quarterly drop although at a slowing pace. The lower mid-market held broadly stable, while the upper mid-market fell 6%. Q3 volumes were 10% below Q3 2025, but over the first nine months of 2026, deal volume remained 7% above 9M 2025. Disclosed value, a less reliable indicator given low disclosure rates, was down 3% over the quarter.
This decline remained limited given the macroeconomic disruption, reflecting the structural resilience of the eurozone mid-market. The energy shock linked to the Iran conflict pushed inflation well above target, prompting the ECB to raise its deposit rate for the second time this year in September, to 2.50%. Over the same period, the broader M&A market contracted far more sharply: global M&A value fell 41% quarter-on-quarter to $993bn, the first quarter below $1tn since Q2 2025, as the number of megadeals dropped(2).
(1) Q2 2026 figures have been revised with the latest available data
(2) source: LSEG data / Reuters, 02.10.2026
Eurozone mid-market activity (€15–500m) in volume (# deals) and value
Source : Argos Index© mid-market / Epsilon Research
Eurozone mid-market activity (€15–500m) in volume (# deals)
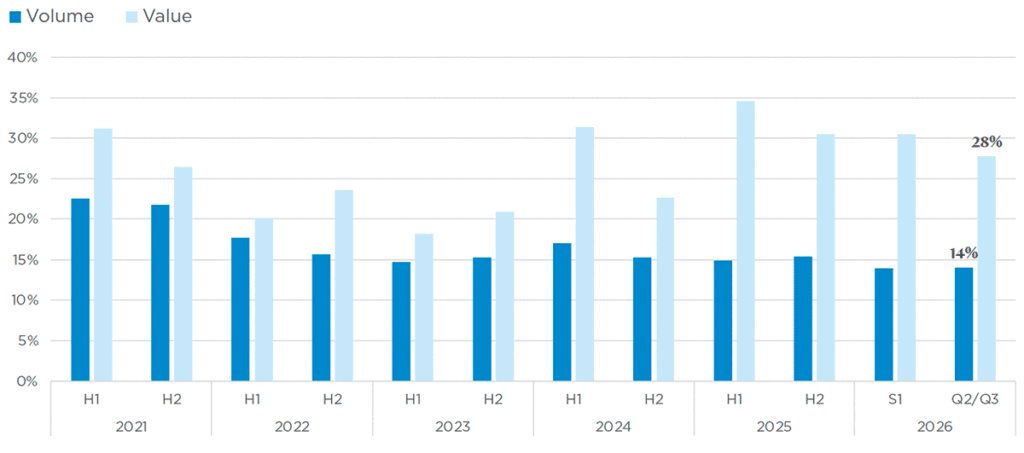
Investment fund activity held up over the quarter, backed by high direct lending volumes(1): the estimated number of LBO deals rose 3% quarter-on-quarter. 9M 2026 activity was in line with 9M 2025, and the LBO share(2) of mid-market M&A over the last six months remained stable at 14% in deal count. After a first half concentrated on fewer, larger buyouts, sponsors tilted towards smaller tickets in Q3, as higher financing costs weighed more on larger leveraged deals.
(1) Source: Pemberton European Mid-Market Monitor Q3 2026
(2) Does not include build-ups
Share of LBO in Eurozone Mid-market M&A